
If you are sitting at your kitchen table with a stack of bills, crying because you cannot make the numbers work, I understand.
If you feel sick when the telephone rings, are afraid to open the mail, or lie awake imagining everything else that might go wrong, I understand that too.
I am not going to tell you to stop worrying as though your problems are imaginary. I know what it is like to have real bills, real debt, and no obvious way to produce the money you need. I also know how fear can make it nearly impossible to think clearly enough to find your next step.
Maybe you spent more than you should have. Maybe your income never covered ordinary life. Maybe illness, job loss, caregiving, repairs, or growing interest pushed an already-tight household over the edge. Maybe several things happened together, as they did for us.
Whatever brought you here has already happened. You can learn from it, but you cannot go backward and unspend the money or prevent the emergency.
Shame is not a repayment plan.
Beating yourself up may feel like taking responsibility, but it does not pay a bill, lower an interest rate, or put food on the table. Responsibility begins when you look at the facts without turning them into a verdict about your worth.
You may not be able to repair your entire financial life today. That does not mean there is nothing you can do today.
I Know What Financial Fear Feels Like
In 2008, I spent many hours with our checkbook open, trying to fit bills inside an income that could no longer hold them.
My husband was our family’s main breadwinner. I worked part-time jobs, but our son was disabled and going through surgeries and physical therapy. There was no simple way for me to “just work more,” and my husband was already working as much as he could.
We had been barely getting by, using credit whenever the house, the car, or ordinary life handed us an expense we could not absorb. The debt was not from vacations, fancy cars, designer clothes, or extravagant shopping. Much of it came from necessities—groceries, gasoline, and traveling to the hospital while caring for our son.
We had no margin. Whenever life cost more than our income could absorb, the difference went onto credit.
Eventually, accumulating interest and growing payments made the debt impossible for us to service. I spent sleepless nights with my thoughts racing, imagining every terrible outcome that might come next. I was afraid to answer the telephone because creditors were calling. Every unfamiliar noise in the house made me fear that something else had broken.
I felt ashamed and believed everyone else had a perfect life while ours was the one in which something always went wrong. Then something clicked inside me:
This is where you are. This is what you have to work with.
That was not giving up. It was finally beginning from the truth.
I Was Not Spared the Struggle, but I Was Not Abandoned in It
I cannot tell this story honestly without acknowledging God’s hand in it.
He did not make the debt disappear. We still had to make difficult decisions, live on very little, and spend years working our way out. But when fear raced ahead to every possible disaster, God gave me enough peace to think, enough strength to take the next step, and enough endurance to keep going.
Looking back, I can see that we always had what we truly needed. We had a roof over our heads, food on the table, our son’s medicine and doctors, and a dependable enough vehicle to get my husband to work and our son to his appointments. We did not have an impressive house, expensive clothes, or vacations—but we were not left out in the cold.
Things could have been considerably worse. My husband could have remained unemployed for months. The combined strain of caregiving and financial hardship could have destroyed our marriage. Instead, we were given enough provision and endurance for the season we were living through.
I was not spared the struggle, but I was not abandoned in it.
Trusting God did not mean ignoring the bills. It gave me the strength to face them.
Slow Down Before You Decide What to Do
Financial fear makes everything feel equally urgent. The loudest caller seems like the most important creditor, and every decision feels as though it must be made immediately. That is when people may borrow from another expensive source, hire the first company promising relief, or agree to a payment they cannot maintain.
Slowing down does not mean ignoring the problem. It means refusing to let panic make the decision for you.
Taking action does not always mean immediately paying everything off. Sometimes taking action means gathering accurate information so you can finally make a workable decision.
Write down:
- What must be handled today or this week?
- What can wait while I gather information?
- What happens if each bill is paid late?
- Which companies can I call about hardship assistance?
- What payment can my household realistically maintain?
- What must I verify before signing or paying anyone?
Moving quickly and moving forward are not always the same thing. Collect the facts, ask questions, and give yourself enough time to understand the decision in front of you.
Pay the Bills That Protect Your Household First
When we did not have enough for everything, I protected the things our family could not function without: housing, food, electricity, insurance, necessary medication, and transportation.
My husband needed the car to continue earning our income, and I needed it to get our son to medical appointments. These were our non-negotiables because they kept us housed, safe, healthy, and able to move forward.
When money is short, pay according to consequences—not according to which company is making the most noise.
Protect housing, essential utilities, food, necessary healthcare, transportation needed for work or medical care, important insurance, and court-ordered obligations. Then look at the remaining bills.
For each one, ask what happens if it is not paid, how quickly that consequence occurs, and whether the company offers a hardship plan, temporary reduction, due-date change, or payment arrangement.
Sometimes there will not be enough to keep every account current. That is frightening, but treating every bill as equally urgent will not protect your household. Cover the necessities, communicate with the remaining creditors, and investigate your options.
Learn What Debt Options Are Available
Our situation began changing when I admitted that our existing payment arrangement was impossible and started looking for another path.
I eventually enrolled in a debt-settlement program. I deposited money into an account each week, and as it accumulated, the company negotiated settlements with our creditors. The weekly amount was considerably less than the credit-card payments I had been trying—and failing—to maintain.
It was not quick or painless. Our credit was damaged. One creditor sued me, and I had to go to court. The company had legal help available and guided me through what I needed to do, but it was still frightening. The process took approximately four years.
Debt settlement was the workable option I found for our family at the time. It gave us a payment we could manage and a path we could follow. That does not make it the right choice for everyone.
Depending on the situation, other possibilities may include:
- Paying the debt yourself while reducing expenses or increasing income
- Asking creditors directly about hardship programs, lower rates, waived fees, or temporary payment changes
- Working with a reputable nonprofit credit counselor or entering a debt-management plan
- Using a consolidation loan when its total cost and payment are genuinely better
- Negotiating a repayment plan or settlement directly with a creditor
- Carefully investigating a debt-settlement program and its risks
- Consulting a qualified bankruptcy attorney to understand the protections and consequences
- Seeking legal assistance immediately if a creditor sues you
I cannot tell another household which option is right for them. I am listing these possibilities because fear thrives when you believe you have no choices. Learning what is available gives you questions to ask and somewhere to begin.
Before hiring anyone, understand every fee, verify the company independently, and get its promises in writing. Be cautious with anyone guaranteeing a result or pressuring you to act immediately. Debt settlement can involve fees, damaged credit, growing interest and penalties, collection activity, lawsuits, and possible tax consequences.
You do not need to make a perfect decision while under pressure. Gather reliable information, understand the consequences, and choose the most workable next step available to you.
This article shares my personal experience and general educational information. It is not individualized financial, legal, or tax advice.
Would You Like a Little Practical Encouragement Each Week?
If this article helped you feel less alone, I would be glad to have you join me for the Home Journal.
Each Friday, I share practical homemaking, simple recipes, home-economy ideas, and encouragement for making the most of what you have—without perfection, pressure, or shame.
Save Something While You Rebuild
Once we entered the program, life did not stop producing problems. I began paying myself first, even when I could only put $20 into an envelope. I cannot remember whether I did it weekly or with each paycheck. The exact amount and timing mattered less than beginning.
I kept setting aside small amounts until an unexpected expense arrived—and for the first time, we had money available to cover it instead of creating another debt.
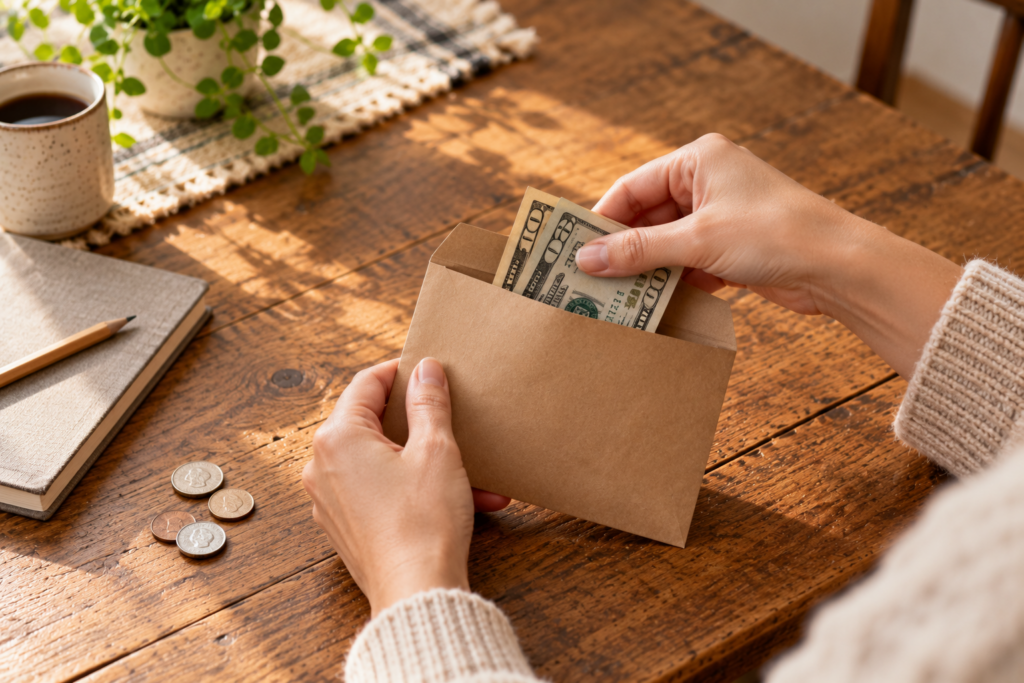
A small emergency fund can interrupt the cycle in which every unexpected expense becomes new debt.
Advice about saving three to six months of expenses can sound absurd to someone struggling to find $20. Begin with $1, $5, $10, or $20—whatever you can manage after protecting the necessities. Then work toward $100 and, eventually, enough to handle one ordinary household problem.
Paying yourself first does not mean withholding money needed for housing, food, medicine, or heat. It means including some amount of saving in your plan whenever there is room, rather than waiting for money to be accidentally left over.
If you can maintain your required debt payments, a small starter fund may keep the next repair from going straight onto a card. Once you have a basic cushion, you can direct more toward high-interest debt while continuing a modest savings habit.
If you are already behind, cannot cover necessities, or face legal action, your order may need to be different. Protect the household and seek qualified guidance. The goal is a plan that reduces existing debt without leaving you completely exposed to the next ordinary problem.
And if you must use your savings, that is not failure. That is what the money was there to do. Start rebuilding it with the next small amount you can manage.
If home repairs are one of your biggest worries, you may also find my guide to How to Afford Home Repairs Without Stress helpful.
Use What You Have to Lower the Grocery Bill
During those years, I kept a strict grocery budget of $100 per week. That included laundry detergent, dish soap, cleaning products, paper goods, and other household necessities—not only food. If we needed several household products, there was less available for meals.
Instead of deciding what I wanted to cook and purchasing every ingredient, I reversed the process:
We have this. This is on sale. What meals can I make from those things?
I checked the refrigerator, freezer, and pantry before shopping. I kept useful staples on hand, bought sale foods that worked with what we already owned, and learned to cook creatively from scratch. We did not eat extravagantly, but we ate well. I still use that method today.
The $100 figure was our number at that time, not a recommendation for every household today. The repeatable system is simple:
- Set a realistic weekly amount that includes food and household supplies.
- Shop your refrigerator, freezer, and pantry first.
- Use store sales to complete meals rather than build the entire plan around cravings.
- Restock dependable pantry foods when the price is favorable.
If you want more help building meals around what you already have, read How to Meal Plan When Food Prices Keep Rising.
Sometimes we postponed a purchase, made do with something broken, or simply went without. I also discovered free and inexpensive ways to enjoy life. The library became exciting. Sometimes our entertainment was a rented movie and a $5 pizza.
It was not glamorous. Progress happened one homemade meal, one small deposit, and one problem handled without new debt at a time.
Break the Paycheck-to-Paycheck Pattern Gradually
Living paycheck to paycheck does not always mean someone needs a fancier budget. Sometimes the essential expenses genuinely consume all the income.
Begin by calculating the minimum amount required to operate your household for one month: housing, essential utilities, basic food, medication, necessary insurance, and essential transportation.
If those necessities regularly exceed your income, cutting a few subscriptions will not permanently repair the math. Something structural may need to change—income, housing, transportation, debt payments, or another major expense. Assistance programs or hardship arrangements may also be necessary while you work toward a longer-term solution.
If the numbers nearly work, begin creating a small gap between one paycheck and the next. That gap might start as $20 in an envelope. Over time it may become one bill paid ahead, then one week of necessities, and eventually a month of essential expenses.
None of this happens in one paycheck. Slow does not mean it is not working.
Make a Simple Job-Loss Plan
During the 2008 recession, my husband began a job and was let go approximately two weeks later because the company eliminated the part of the business where he had just begun working.
We were fortunate that he found another job almost immediately. The new position paid less, which intensified an already difficult situation, but we maintained income and health-insurance coverage.
Sometimes surviving a setback means accepting a temporary step down so the household can keep moving while you determine what comes next.
Prepare one page containing:
- Your bare-bones monthly household number
- Expenses and automatic payments you could pause
- Current employment history, résumé, references, and useful contacts
- Information about unemployment benefits and health-insurance alternatives
- Creditors and providers to contact about hardship arrangements
- The temporary work your household could consider while pursuing a better position
A job-loss plan cannot guarantee quick employment. It prevents you from having to locate every document and discover every number while already in shock.
Why Money Fear Can Remain After the Crisis
Paying off our debt did not instantly make everything perfect. The settlement process took approximately four years, and rebuilding savings took several more. We continued living frugally because we never wanted to return to that position.
Today, we have a better-funded rainy-day account and more savings. When we use a credit card, we pay the balance before it accumulates interest. We can sometimes pay cash for expenses that once would have created debt.
That still amazes me.
Do I feel like a billionaire who will never worry about money again? No. You never completely know what life will bring. Some of the fear I developed during 2008 remains deeply rooted.
But now I also remember something else: I survived it.
I learned that I can face an ugly situation, make a plan, live with less, remain patient, and slowly build something better. Fear may still speak, but it is no longer the only evidence I have. I also have proof that I can respond.
If money worry follows you after your circumstances improve, place each fear beneath one of three headings:
- Happening now
- Might happen later
- Outside my control
Act on what is happening now. Make a reasonable preparation for what might happen later. Then practice releasing what is outside your control instead of treating every possibility as today’s emergency.
I sometimes say that I want to be rich without looking rich. I would rather quietly have financial margin than spend everything trying to appear prosperous. That does not mean I am perfect, never want anything, or never compare my life with someone else’s.
Contentment is a hard beast to catch.
It means I understand what financial breathing room is worth, and I am less willing to trade it for things that only make us look successful.
You Do Not Have to Solve Everything Today
Financial recovery is usually quiet and slow. It may take months or years to change your situation, but you do not have to wait until the end to feel the first signs of relief.
Relief begins when you see the problem clearly and know what you are doing next. The first bill you prioritize, the first call you make, the first option you investigate, and the first $5 you save all count.
You do not have to solve everything today. You only need to stop standing still because you are afraid.
If you are reading this while frightened, overwhelmed, or wondering how you will ever straighten everything out, I hope my story has helped you breathe a little easier.
You may have difficult decisions ahead, and your situation may take time to change. But you have options. Slow down, gather accurate information, ask for help when you need it, and take the next workable step.
Please remember that a difficult financial season is not a verdict on your worth, nor does it have to become the rest of your life. Small steps count. Slow progress counts. Beginning again counts.
From my hearth to yours,
Becky
Leave a Reply